
For most small mortgage firms, the best CRM for mortgage brokers small business is Jungo when the firm already runs Salesforce, and BNTouch when it wants a standalone system at a predictable price. That split matters, because the strongest tool for a Salesforce firm is a poor buy for a solo broker who has never opened Salesforce, and the cheapest tool for a solo broker may lack the routing a ten person team needs.
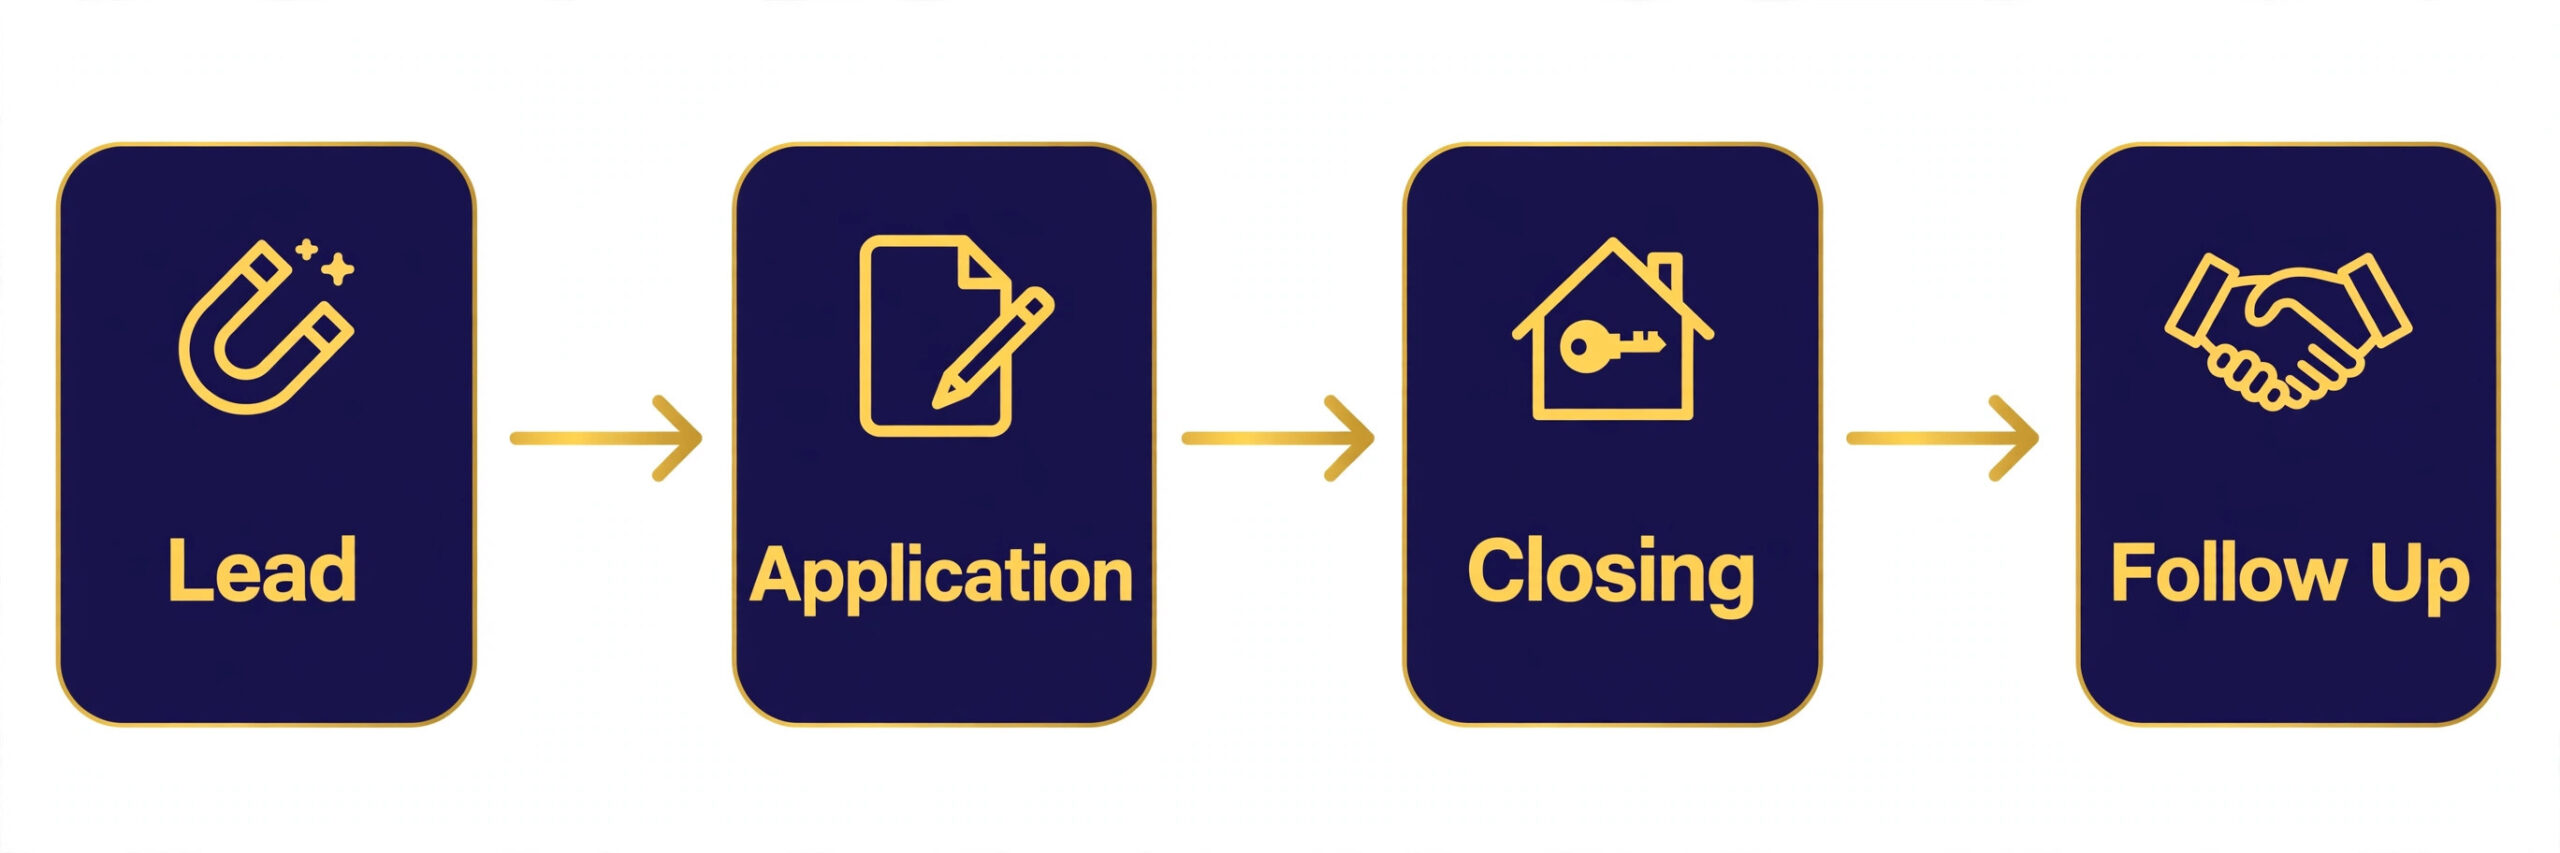
A mortgage CRM is not a loan origination system and it is not a point of sale system, and confusing those three buys the wrong tool. A CRM manages relationships and pipeline from first contact through closing and past client follow up. A loan origination system originates the loan file, and a point of sale system digitises the borrower application. A small firm needs to know which job it is buying before it signs.
This guide compares eight tools on the same questions. What does the price become at the real seat count, which loan origination systems does it truly sync with, how strong is automated nurture, and where does each tool fall short. Prices are starting points checked at writing time, so confirm the current price on the vendor page before you buy.
Mortgage Broker Tools at a Glance
Read the table as a shortlist, not as a ranking. The cheapest tool suits a solo broker perfectly, while the quote led platform suits a brokerage that wants enterprise nurture. Pick three finalists, then read their full sections before committing to an annual plan. Use this table to start choosing the best CRM for mortgage brokers small business for your size and budget.
| Tool | Starting price | Best for |
|---|---|---|
| Jungo | mortgage firms already running Salesforce | From $96 a user a month in recent comparisons |
| Surefire | brokers focused on automated nurture | Check the vendor page |
| Floify | brokers needing a borrower point of sale | From $79 a user a month |
| BNTouch | solo brokers and small teams wanting one system | From $165 a month for a solo user |
| Total Expert | larger small brokerages wanting enterprise nurture | Check the vendor page |
| Shape | mid size teams needing lead routing | Check the vendor page |
| Insellerate | teams of five to twenty loan officers | About $65 to $95 a user a month in recent comparisons |
| Bonzo | brokers wanting an engagement layer | Check the vendor page |
Why best CRM for mortgage brokers small business Beats a General Sales CRM
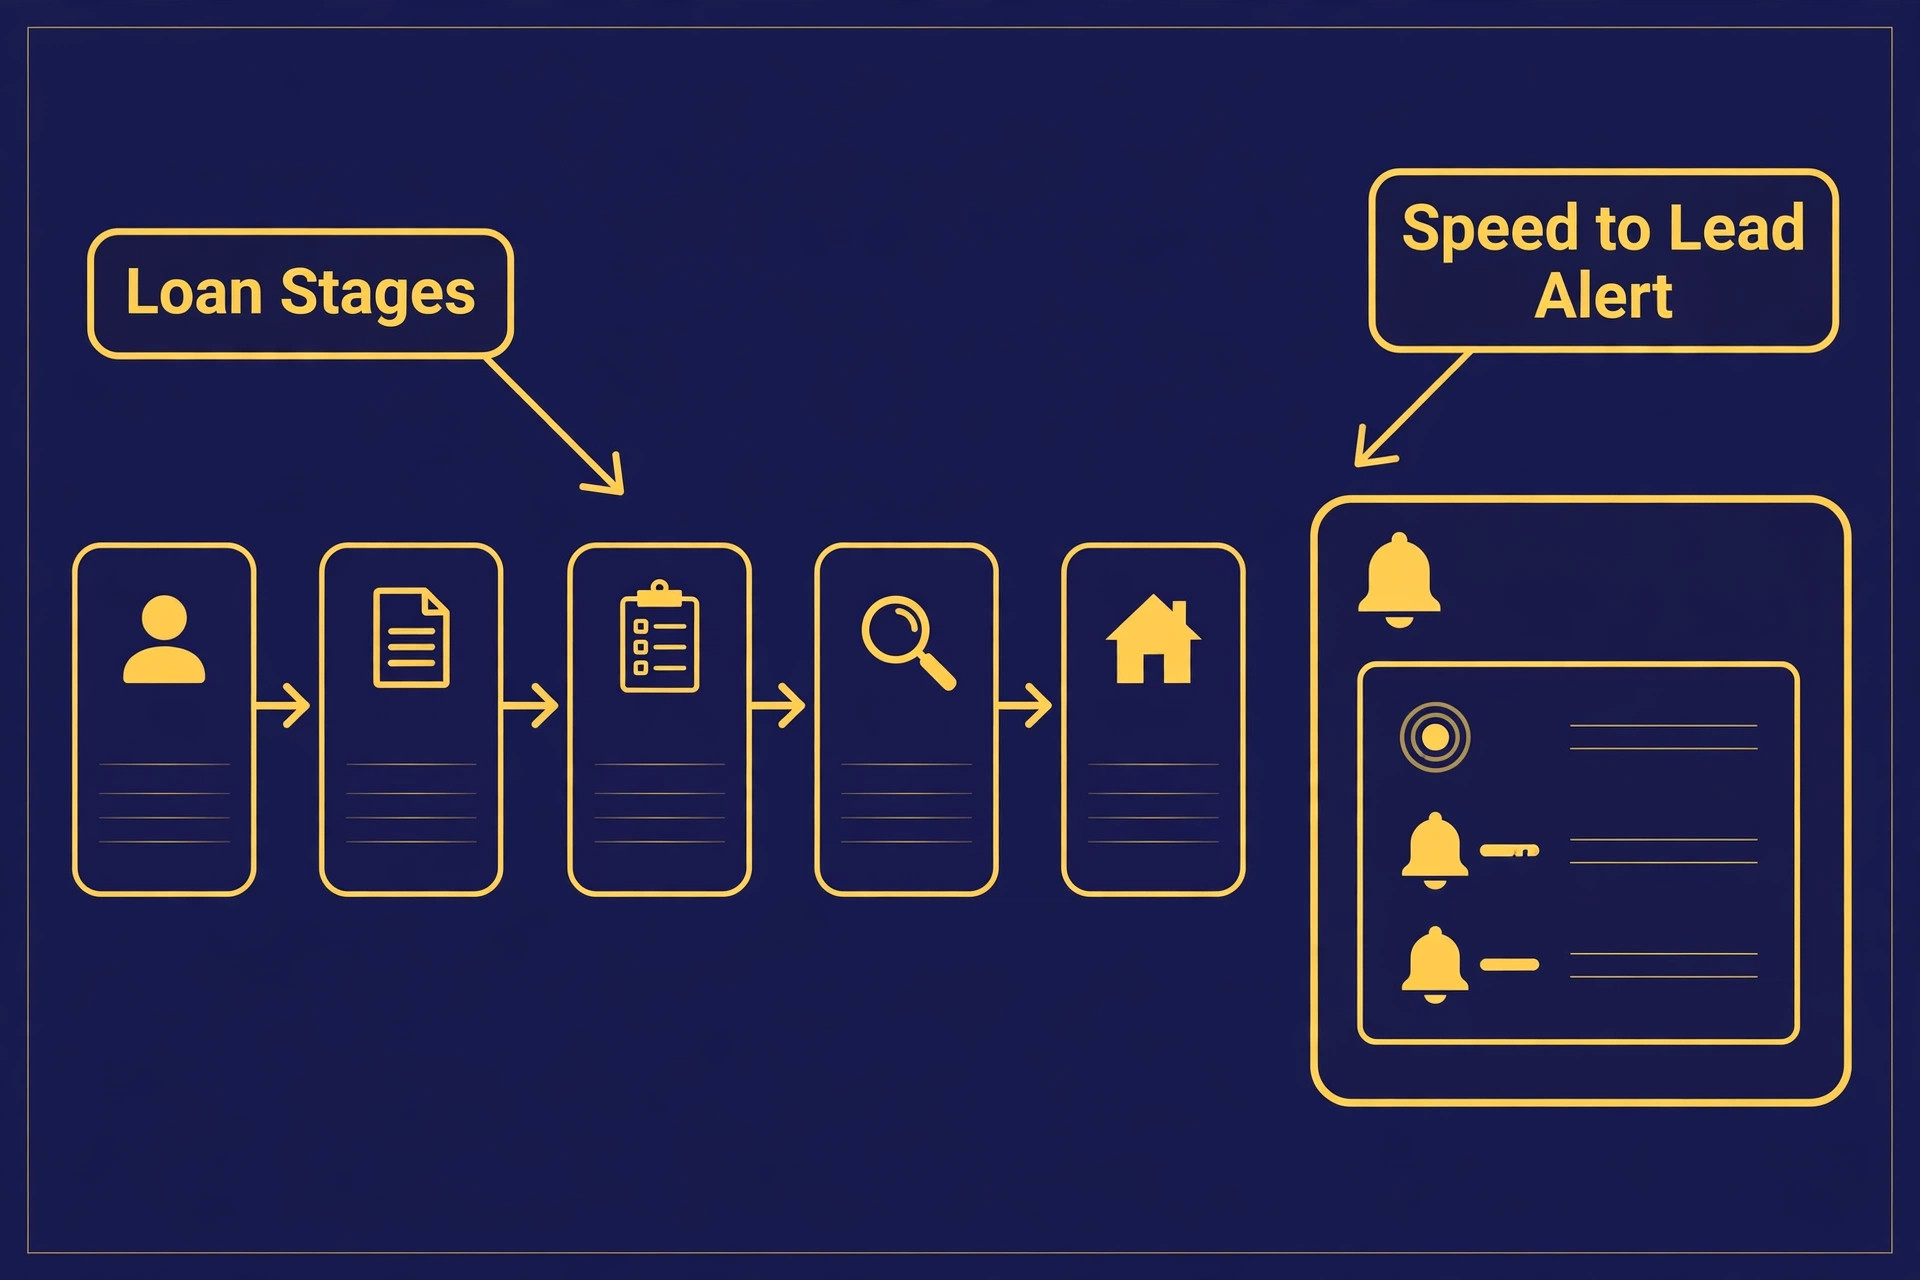
A general CRM can store contacts, but it does not understand a loan. A borrower has a pre qualification status, a loan stage, a referral partner, a closing date and a post close timeline, and the follow up that works in month one is useless in month nine. A mortgage CRM holds those fields as standard, runs campaigns built for long buying cycles and tracks a contact from first enquiry through closing and past client follow up without custom building.
Speed is the second difference, and it is measurable in lost deals. Inbound leads go cold fast, and a CRM that alerts the right loan officer instantly, assigns by rota or territory and starts a text and email sequence within minutes will convert more of the same lead flow than a prettier tool that batches alerts. Small brokerages cannot outspend large teams on lead buying, so they have to win on response speed and follow up discipline, and the CRM is where that discipline lives.
The third difference is compliance and content. Mortgage marketing must stay accurate, fair and properly disclosed, and a specialist tool ships with compliance reviewed assets, audit trails and consent handling for calls, texts and emails. A general CRM leaves that work to the broker, which is where mistakes creep in. Test the compliance workflow, not just the campaign library, before choosing.
Start the trial with a real week of work, not with a demo account filled with perfect test data. Load your actual timetable, your real customers and your true prices, then ask the team to run the daily routine exactly as they would after launch. A trial that mirrors real work exposes slow screens, missing fields and confusing steps before any money changes hands. If a task takes three clicks in the demo and seven in real use, that gap will cost hours every week.
Train on one workflow at a time, starting with the job that earns money fastest. Staff who learn booking, payment and cancellation in week one will trust the system, while staff who sit through a full feature tour will remember little of it. Short daily practice, using real examples from the previous day, builds confidence faster than a long training day that nobody enjoys.
Agree on response times and support hours in writing, especially if the business trades evenings or weekends. A support team that answers only on weekday mornings is little help when the system fails on a Saturday. Ask for the real support channel, test it during the trial, and note how long a genuine question takes to reach a person who can fix it.
Eight Systems, Reviewed One by One
Jungo
Jungo is the pick for From $96 a user a month in recent comparisons. It is built on Salesforce, with loan tracking, marketing automation, post close programmes and reporting shaped for mortgage work. It integrates with major loan origination systems, so pipeline, marketing and loan status can live in one record rather than across three tools. At mortgage firms already running Salesforce, it sits in a price band a small business can judge against the hours it saves or the revenue it protects.
The limit is cost and setup, because Salesforce licensing, configuration and training add to the per user price, and a solo broker without Salesforce experience will need help to launch well. Choose Jungo if the job above matches your daily work and the price fits your budget at your real size. Skip it if that job is only a small part of what you need, because a tool bought for one job rarely excels at a different one.
Surefire
Surefire is the pick for Check the vendor page. It is now part of ICE Mortgage Technology, with omnichannel automation across email, text and print, plus a large library of compliance ready marketing assets. A broker who loses deals to slow follow up gets ready made campaigns that keep borrowers and referral partners warm for months. At brokers focused on automated nurture, it sits in a price band a small business can judge against the hours it saves or the revenue it protects.
The limit is transparency, because pricing is quote only in recent comparisons, and enterprise heritage means a small firm should confirm seat minimums, contract length and onboarding fees in writing. Choose Surefire if the job above matches your daily work and the price fits your budget at your real size. Skip it if that job is only a small part of what you need, because a tool bought for one job rarely excels at a different one.
Floify
Floify is the pick for From $79 a user a month. It is a point of sale system, not a full CRM, and it streamlines the borrower side with an interview style application, secure document collection, progress tracking and communication for borrowers and agents. Paired with a CRM, it gives borrowers a modern application experience. At brokers needing a borrower point of sale, it sits in a price band a small business can judge against the hours it saves or the revenue it protects.
The limit is scope, because it does not replace pipeline management, nurture campaigns or referral partner marketing on its own. Buy it as the application front end, and budget for a CRM alongside it, rather than expecting one tool to do both jobs. Choose Floify if the job above matches your daily work and the price fits your budget at your real size. Skip it if that job is only a small part of what you need, because a tool bought for one job rarely excels at a different one.
BNTouch
BNTouch is the pick for From $165 a month for a solo user. It covers call, text and video follow up, pipeline tracking, marketing automation and loan status updates in one system built for mortgage. A solo broker gets multi touch follow up without stitching a dialler, a CRM and a marketing tool together. At solo brokers and small teams wanting one system, it sits in a price band a small business can judge against the hours it saves or the revenue it protects.
The limit is price at team size, because the solo price rises with added users, so a growing team should price five seats, not one, before comparing it with per user rivals. Choose BNTouch if the job above matches your daily work and the price fits your budget at your real size. Skip it if that job is only a small part of what you need, because a tool bought for one job rarely excels at a different one.
Total Expert
Total Expert is the pick for Check the vendor page. It covers CRM, marketing automation, co marketing with referral partners and post close engagement for mortgage and financial firms. A brokerage that lives on referral partner business will value the co branded campaigns and partner reporting most. At larger small brokerages wanting enterprise nurture, it sits in a price band a small business can judge against the hours it saves or the revenue it protects.
The limit is access, because pricing is quote only and the platform is built for larger teams, so a solo broker may pay for enterprise depth and sales led onboarding it does not need. Choose Total Expert if the job above matches your daily work and the price fits your budget at your real size. Skip it if that job is only a small part of what you need, because a tool bought for one job rarely excels at a different one.
Shape
Shape is the pick for Check the vendor page. It covers lead routing, pipeline management, marketing automation and reporting for mortgage teams, with a focus on getting each lead to the right loan officer fast. A team buying leads from several sources gets routing rules and speed to lead visibility in one place. At mid size teams needing lead routing, it sits in a price band a small business can judge against the hours it saves or the revenue it protects.
The limit is published pricing, because current prices sit behind sales conversations in recent comparisons, so a small firm cannot budget accurately until it receives a written quote at its real seat count. Choose Shape if the job above matches your daily work and the price fits your budget at your real size. Skip it if that job is only a small part of what you need, because a tool bought for one job rarely excels at a different one.
Insellerate
Insellerate is the pick for About $65 to $95 a user a month in recent comparisons. It covers lead distribution, pipeline management, dialler tools and automation for mortgage teams that work high lead volumes. A team that distributes leads daily will feel the difference between a CRM that records leads and one that routes them with discipline. At teams of five to twenty loan officers, it sits in a price band a small business can judge against the hours it saves or the revenue it protects.
The limit is verification, because the price range comes from third party comparisons rather than a published price page, so confirm the current per user figure and any dialler fees before budgeting. Choose Insellerate if the job above matches your daily work and the price fits your budget at your real size. Skip it if that job is only a small part of what you need, because a tool bought for one job rarely excels at a different one.
Bonzo
Bonzo is the pick for Check the vendor page. It covers automated text, email and voice engagement, pipeline follow up and referral partner touchpoints, and it works as an engagement layer on top of a full CRM for many firms. A broker whose CRM is sound but whose follow up is slow gets speed without replacing the system of record. At brokers wanting an engagement layer, it sits in a price band a small business can judge against the hours it saves or the revenue it protects.
The limit is scope, because it is not a full system of record on its own for most firms. A broker without a CRM still needs one, so price Bonzo as an addition, not as a replacement. Choose Bonzo if the job above matches your daily work and the price fits your budget at your real size. Skip it if that job is only a small part of what you need, because a tool bought for one job rarely excels at a different one.
Best Pick by Firm Shape
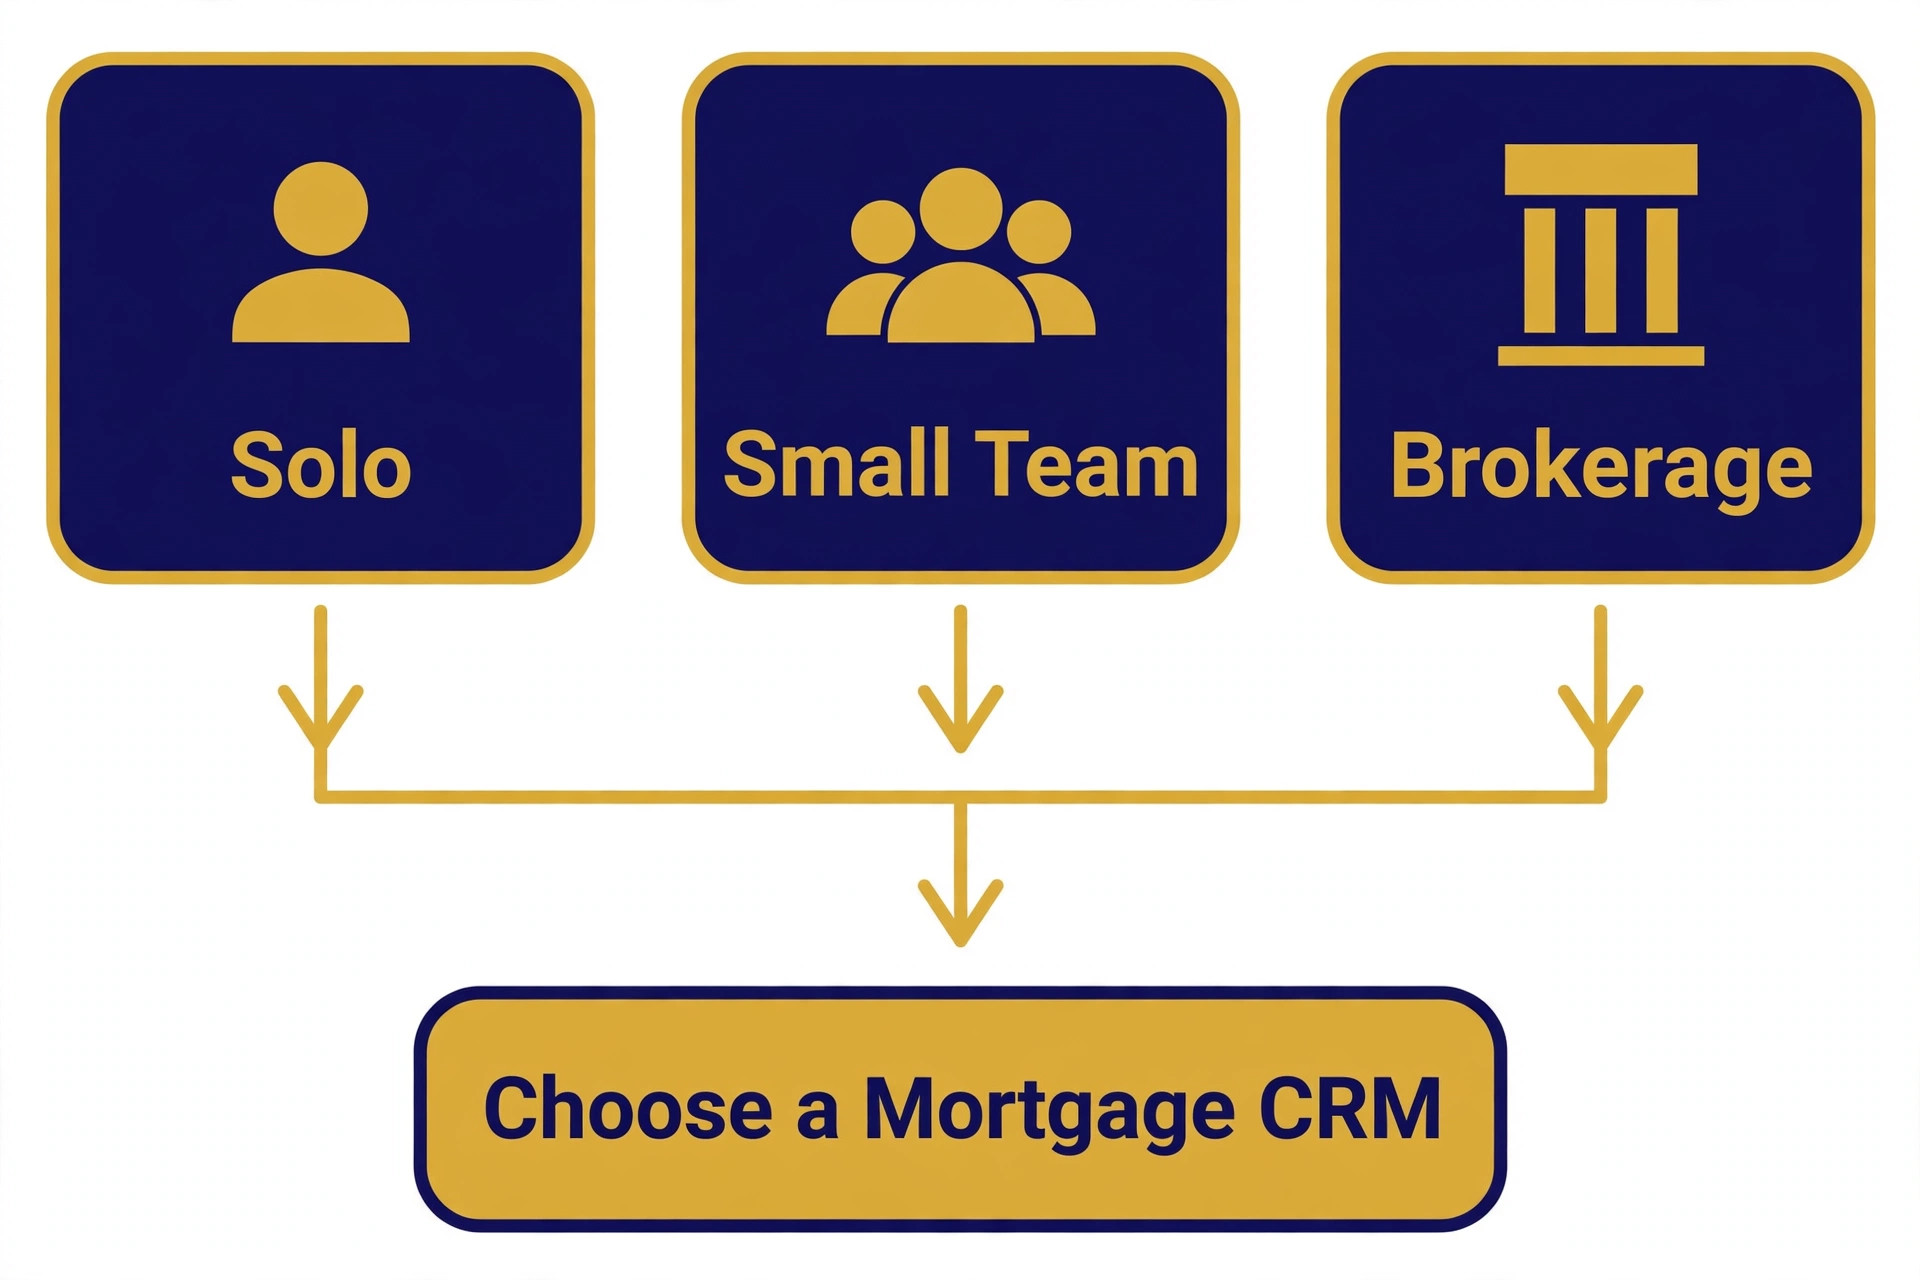
The right CRM changes with the shape of the firm. A solo broker, a small team and a brokerage are buying different systems, even when they browse the same category pages. Use this table to match the pick to the job, then confirm the fit in a trial with real lead sources connected. That matching step turns a general search for the best CRM for mortgage brokers small business into a shortlist that fits real work.
| Job | Best pick | Why it wins |
|---|---|---|
| Solo broker | BNTouch | One system for calls, texts, video and pipeline |
| Small team | Insellerate | Lead distribution and dialler discipline |
| Brokerage on Salesforce | Jungo | Deepest reporting on the Salesforce platform |
| Application experience first | Floify | Modern borrower application and document flow |
The Compliance Checklist Before You Pay
Run through this checklist on every finalist before signing. A CRM that fails two or more items will cost more in missed loans and compliance risk than it saves in subscription fees. Run the same checks when comparing the best CRM for mortgage brokers small business, because marketing that looks good in a demo must also stay compliant in daily use.
– Check that every text and email campaign records consent, with opt out handling that works automatically and leaves a clear audit trail. – Check that marketing assets are reviewed for compliance, with disclaimers and licensing details handled in templates rather than left to each loan officer. – Check that borrower data access is controlled by role, so service staff, loan officers and managers see only what their job requires. – Check that loan stage, referral source and next action are visible on one screen, so a Monday pipeline meeting can run without opening five reports. – Check that lead sources connect automatically, with no manual import step that delays speed to lead or loses source attribution. – Check that contacts, notes and pipeline history can be exported, so the firm is never locked into a tool it cannot leave.

What a Small Mortgage Firm Really Pays
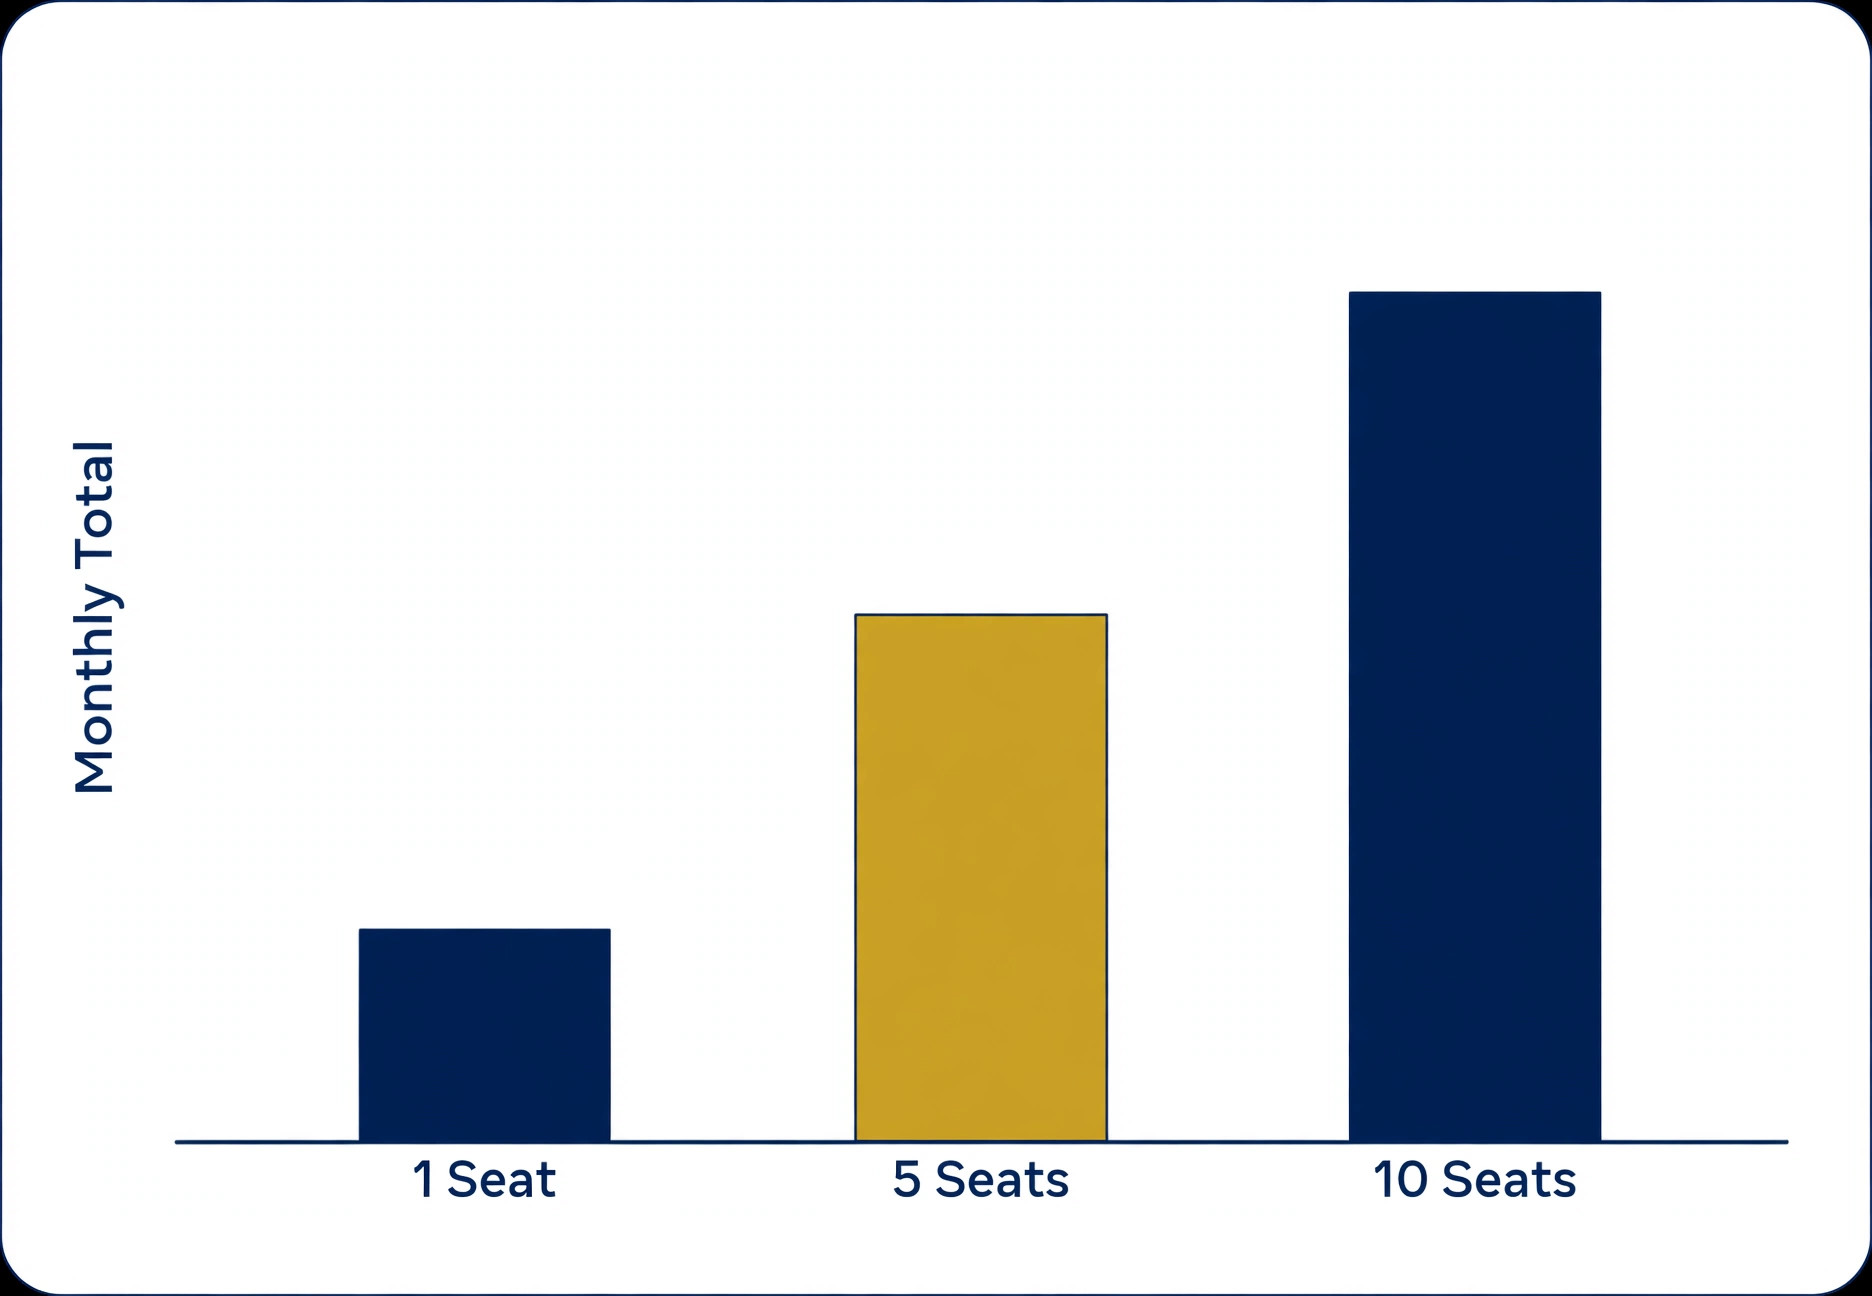
The headline per user price hides the real decision, because seat count, setup fees and add ons move the total by hundreds each month. A solo broker on a 165 dollar plan pays under 2,000 dollars a year, while a five person team on a 96 dollar per user plan pays 480 dollars a month before setup or add ons. Compare totals at the real seat count, not single seat prices. That total is the real price to compare when choosing the best CRM for mortgage brokers small business.
Annual contracts deserve a line of their own. Many mortgage CRMs bill annually, charge onboarding fees and lock the firm in for a year. Before signing, confirm the monthly equivalent, the setup fee, the cancellation terms and what happens to borrower data at exit. A cheap monthly price on a strict annual contract can cost more than a dearer monthly plan that lets the firm leave.
Ask who owns the setup once the vendor team leaves. A tool that needs a champion inside the business will stall if that person is also the busiest operator. Name one owner, give that person protected time in the first fortnight, and write down the three routines that must happen every day. Without an owner, even a strong product drifts back to spreadsheets and group chats within a month.
Watch the first month of reports closely, because the numbers will show whether the new system helps or merely moves work around. Track time spent on admin, missed bookings or unpaid invoices, and customer complaints about the booking or payment step. If those figures do not improve by the end of month one, fix the workflow before blaming the team, because a good tool with a bad workflow still fails.
Mistakes That Lose Mortgage Deals
The most expensive mistake is buying a platform for features the firm never uses. A two person team on an enterprise platform with behavioural targeting and deep partner reporting is paying for capacity built for fifty loan officers, while the leads it does get wait for a reply. Start with the lead flow you actually have, buy the tool that works that flow well, and upgrade when volume proves the need. That discipline matters for any search for the best CRM for mortgage brokers small business.
The second mistake is importing contacts and calling the CRM done. A CRM only earns its fee when campaigns are live, lead sources are connected, alerts reach the right loan officer and the pipeline is reviewed weekly. Firms that skip setup end up with an expensive address book and the same missed leads as before. Block a full setup week before judging the tool.
Check the exit terms before the entry price, because every system in this guide holds data you will need later. Ask for a sample export, open it, and confirm that customer records, history and financial figures come out in a usable form. A vendor that makes leaving hard will also make price rises easy, so treat export quality as a core feature rather than a footnote in the contract.
Keep the customer experience at the centre of every setting you change. A shorter form, a clearer confirmation and a faster payment step will do more for repeat business than a new dashboard feature. Test every change as a customer would, on a phone, in a hurry, with one hand free. If a step feels awkward there, it will feel awkward for every customer who tries it.
How to Test Three Mortgage Finalists in Two Weeks
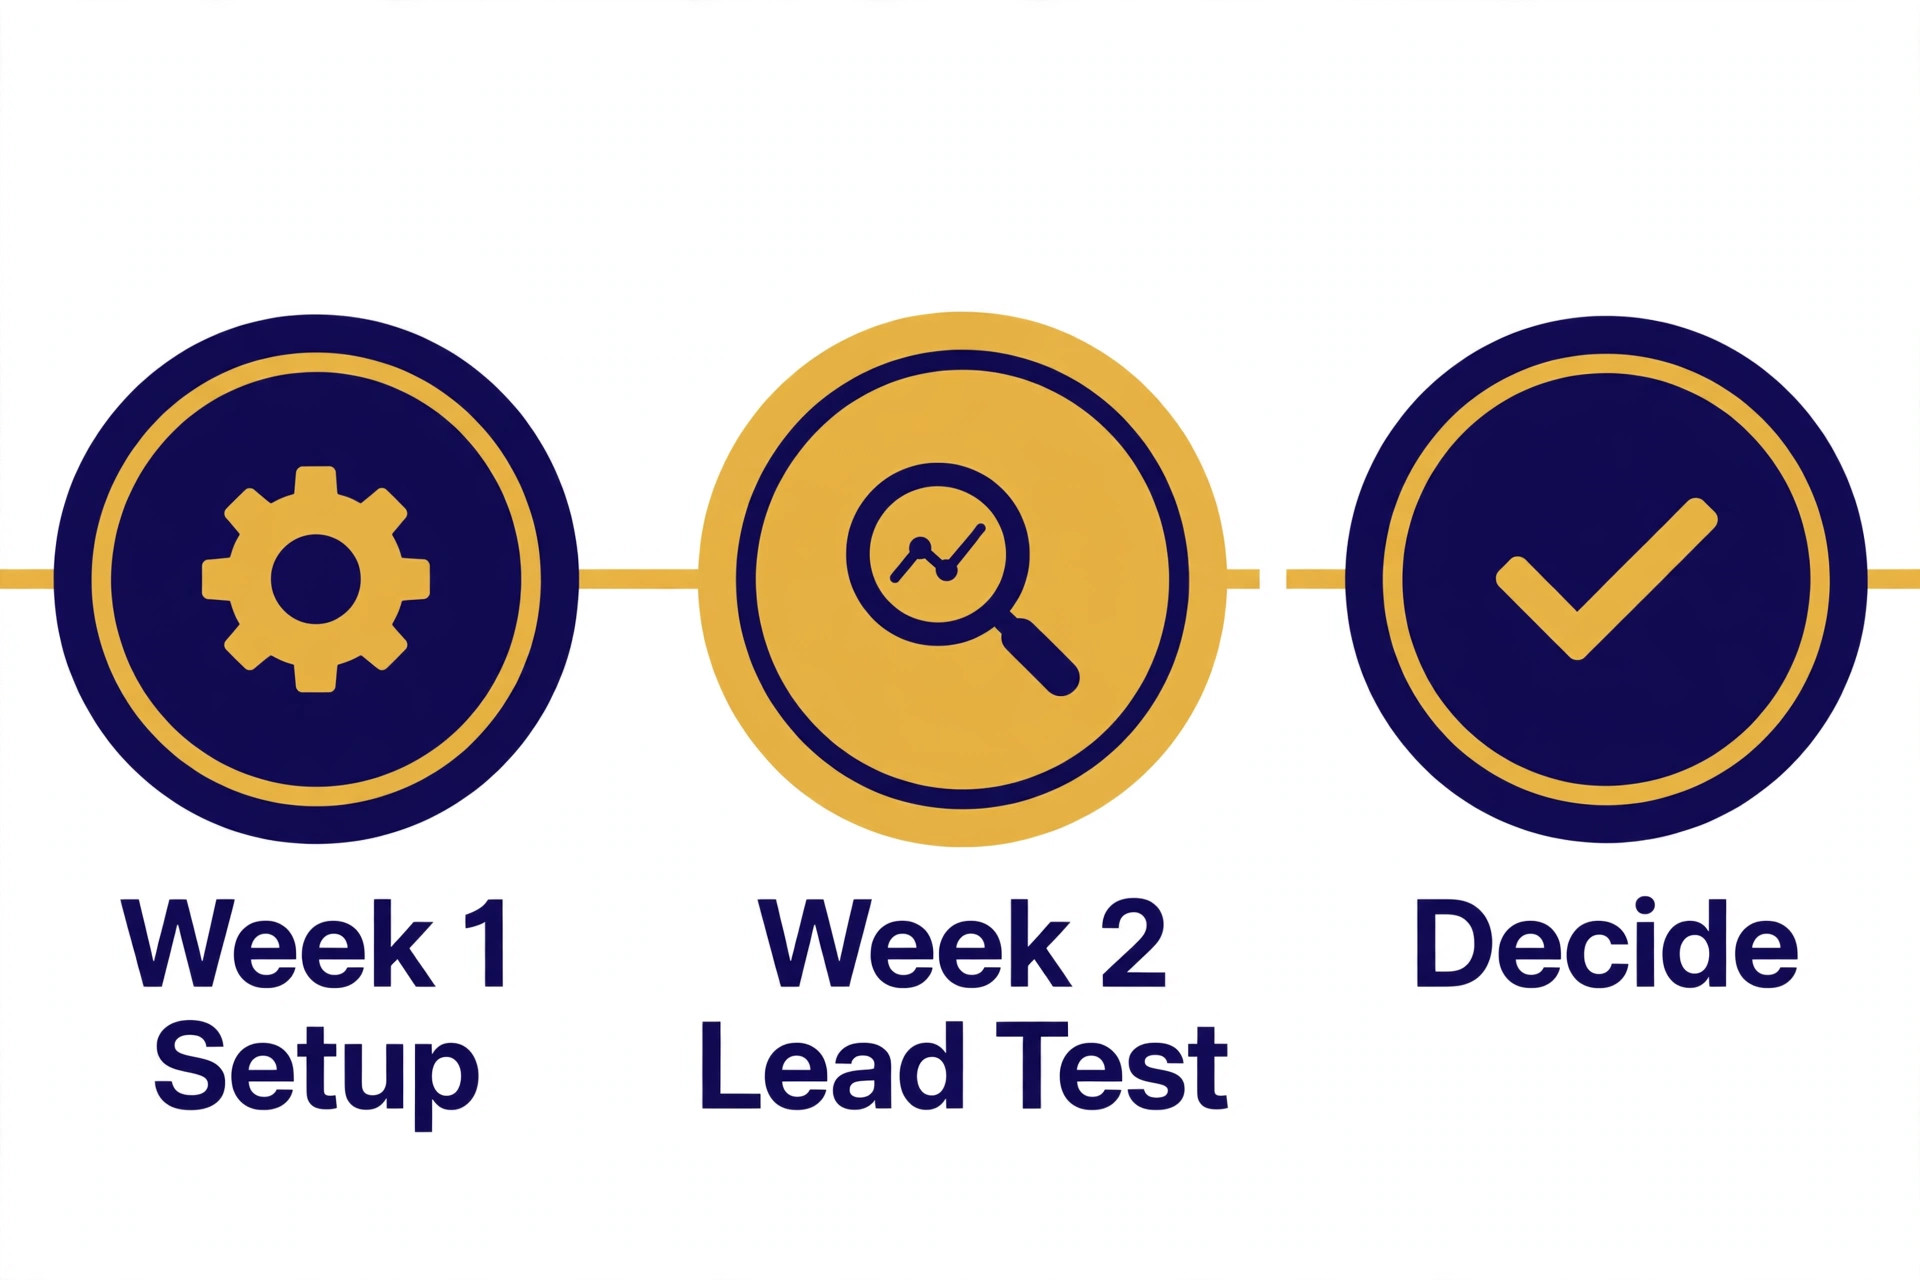
Give each finalist the same real week of work. Load real lead sources, a small set of test borrowers at different loan stages and the actual campaign messages the firm would send, then run speed to lead, follow up sequences and a pipeline review through each system. Score each tool on the same sheet, so the decision rests on evidence rather than on the smoothest sales demo. A fair trial is the only honest way to compare the best CRM for mortgage brokers small business.
Test the loan officer journey on a phone, not on a desktop, because most follow up happens between appointments. Check how fast a loan officer can see a new lead, call it, log the outcome and trigger the next step, and how clear the pipeline looks at a glance. A system that feels fast in week one usually stays fast, while a system that feels slow rarely improves with familiarity.
Price the second year, not the first month, because introductory rates, free trials and launch discounts all expire. Write down the renewal price, the price at the next tier and the cost of the add ons you actually need. A plan that looks cheap at launch and dear at renewal is not cheap, and a plan that stays fair as you grow is worth more than a small saving in month one.
Separate must have features from nice to have features before the demo, and score each finalist only on the must have list. A long feature list looks impressive in a sales call, yet most of those features will never be opened after launch. Three features used daily beat thirty features used once, so buy for the daily work and ignore the rest of the catalogue.
More Reading on Stratilyze
–
[
B
e
s
t
C
R
M
S
o
f
t
w
a
r
e
f
o
r
S
m
a
l
l
B
u
s
i
n
e
s
s
]
(
h
t
t
p
s
:
/
/
s
t
r
a
t
i
l
y
z
e
.
c
o
m
/
b
e
s
t
–
c
r
m
–
s
o
f
t
w
a
r
e
–
f
o
r
–
s
m
a
l
l
–
b
u
s
i
n
e
s
s
/
)
–
[
B
e
s
t
C
R
M
f
o
r
I
n
s
u
r
a
n
c
e
A
g
e
n
t
s
S
m
a
l
l
B
u
s
i
n
e
s
s
]
(
h
t
t
p
s
:
/
/
s
t
r
a
t
i
l
y
z
e
.
c
o
m
/
b
e
s
t
–
c
r
m
–
f
o
r
–
i
n
s
u
r
a
n
c
e
–
a
g
e
n
t
s
–
s
m
a
l
l
–
b
u
s
i
n
e
s
s
/
)
–
[
B
e
s
t
C
R
M
f
o
r
R
e
a
l
E
s
t
a
t
e
A
g
e
n
t
s
S
m
a
l
l
B
r
o
k
e
r
a
g
e
]
(
h
t
t
p
s
:
/
/
s
t
r
a
t
i
l
y
z
e
.
c
o
m
/
b
e
s
t
–
c
r
m
–
f
o
r
–
r
e
a
l
–
e
s
t
a
t
e
–
a
g
e
n
t
s
–
s
m
a
l
l
–
b
r
o
k
e
r
a
g
e
/
)
Frequently Asked Questions About Mortgage Broker CRMs
Is a mortgage CRM different from a loan origination system?
Yes. A CRM manages relationships, pipeline and follow up, while a loan origination system originates and processes the loan file itself. Most firms need both, and the value comes from how well they sync, not from one tool pretending to do both jobs equally well.
Do I need a CRM if I only close a few loans a month?
Yes, if follow up is where deals are lost. Even a solo broker benefits from automatic reminders, post close campaigns and referral partner touchpoints, because a single extra closed loan a quarter can pay for a year of software. The question is which tier fits, not whether follow up matters.
How much should a solo broker budget?
A solo broker should budget the solo plan price plus processing and add on costs, and compare that total with one extra closed loan. A plan near 165 dollars a month is easy to justify if it saves one deal, and hard to justify if the broker never turns on its campaigns. Usage, not price, decides value.
What is speed to lead, and why does it matter?
Speed to lead is the time between a lead arriving and a human response. Leads answered within minutes convert far better than leads answered hours later, because the borrower is still shopping and still near a phone. A CRM earns its fee by alerting the right person instantly and starting follow up automatically.
Can I keep using Floify without a CRM?
You can run applications through Floify alone, but pipeline nurture, referral partner campaigns and long term follow up will still need a system. Many firms pair Floify as the application front end with a CRM as the system of record, and that pairing works well when the two sync cleanly.
What should I check before signing an annual contract?
Check the seat count at real size, the setup fee, the notice period, the price change clause and the data export terms. Ask for the full written quote, test an export during the trial, and confirm what happens to borrower records if the firm leaves. A clear contract protects both sides, and a vague one protects only the vendor. That check is essential when choosing the best CRM for mortgage brokers small business.
The Verdict for Small Mortgage Firms
For most small mortgage firms, BNTouch is the sensible first trial for a standalone system, because it covers calls, texts, video and pipeline at a price a solo broker can model. Firms already on Salesforce should trial Jungo first, and firms whose application experience is the bottleneck should trial Floify alongside a CRM rather than instead of one. That shortlist is a practical way to choose the best CRM for mortgage brokers small business without paying for enterprise depth you will not use.
Whichever tool you shortlist, test it with real leads, real loan stages and a real follow up week before you pay for a year. The best system is the one loan officers actually open, leads reach in minutes, and owners can leave without losing their borrower history. That test, run properly, will choose the tool for you.